Written By: Apoorv Agarwal
Introduction
Goods and Services Tax (GST) was introduced in India on 1st July 2017 with the aim of incorporating different types of indirect taxes into a single tax system. Some of the indirect taxes that were replaced by GST include VAT, Central Excise Duty, Service Tax, Entertainment Tax, and Octroi. One of the major aims of implementing the Goods and Services Tax (GST) was to provide for consistency in tax system and simplify the tax system for goods and services by bringing together many taxes levied by both the central and state governments and most importantly to eliminate the effect of cascading taxes and burdening of consumers with such taxes.[1]
A legislative appellate procedure was also established with the implementation of GST, allowing taxpayers to contest decisions made by the tax authorities. However, the right to appeal under the GST regime is subject to certain conditions, one of the most important being the requirement of making a pre-deposit.
The requirement of pre-deposit serves two purposes. On one hand, it seeks to discourage frivolous or unnecessary appeals which may otherwise be filed merely to delay the recovery of the demand. On the other hand, the law does not require the taxpayer to deposit the entire disputed amount before approaching the appellate authority. Once the prescribed pre-deposit is made, the amount that remains after making the payment as per the provision will generally be protected from being recovered until the case reaches its conclusion, according to the provisions of the GST law.
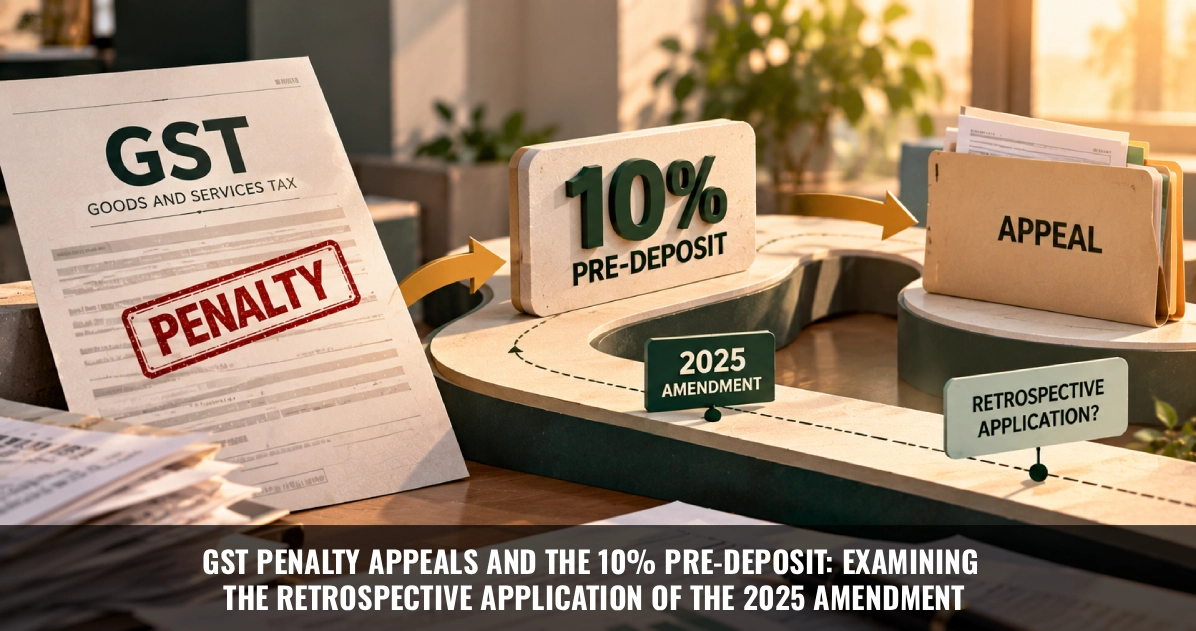
According to Section 107(6) of the Central Goods and Services Tax Act, 2017 (“CGST Act”), there was a need to make the deposit as per the prescribed amount in order to file an appeal before the First Appellate Authority. Prior to the amendment, which was implemented on 1 October 2025, it was necessary to make 100% deposit of tax, interest, fine, fee, and penalty admitted by the appellant and 10% of the remainder disputed tax, subject to a ceiling of ₹25 crore.[2]
However, an important amendment was introduced through Section 129 of the Finance (No. 7) Act, 2025. With effect from 1 October 2025, a proviso was inserted in Section 107(6), specifically dealing with orders which impose penalty without involving any demand of tax[3]. The proviso provides that in a case where an order demands penalty without involving any demand of tax, no appeal can be filed unless the appellant has paid an amount equal to 10% of the said penalty.
The amendment, however, gave rise to an important question i.e. whether the newly introduced requirement of a 10% pre-deposit could be imposed in cases where the proceedings had already commenced before 1 October 2025, but the adjudication order was passed, and the subsequent appeal was filed, after the amendment came into force.
Findings of the Delhi High Court
This issue came up for consideration before the Delhi High Court in Gaurav Jain & Anr. v. Joint Commissioner (Appeals-II), CGST Delhi Zone & Anr[4].. The petitioners in the said case were facing penalty proceedings pursuant to Show Cause Notices (“SCNs”) issued on 25 June 2025. Thus, the proceedings had commenced before the amended proviso to Section 107(6) came into force on 1 October 2025.
The proceedings subsequently resulted in penalty-only orders. When the petitioners sought to avail their statutory appellate remedy, they were required to comply with the newly introduced requirement of depositing 10% of the penalty amount. There were significant fines involved, totalling over ₹693 crore. As a result, just by exercising their right to contest the orders before the appellate body, the petitioners were subject to a substantial financial burden.
The petitioners thus proceeded to approach the Delhi High Court and made an attack on the application of the amendment to the pre-deposit requirement. Their plea was that it would not have been possible to apply the amendment to those proceedings that were pending when the amendment was enacted. The Division Bench consisting of Justices Anil Kshetarpal and Shail Jain agreed with the plea of the petitioners. The Court held that the right of appeal is a substantive and vested right and once it exists it cannot be withdrawn or imposed with a heavier condition unless the legislature expressly or necessarily impliedly provides otherwise.
In light of tax proceedings, the court took into consideration the issuance of the SCN as the appropriate time when the lis commences. In view of the fact that SCNs in the instant case were issued on 25th June 2025, the law on the appeals of the petitioners was decided based on the law that existed on that particular day.
The court noted that the proviso to Section 107(6) that came into effect from 01.10.2025 does not apply to the Petitioners’ Appeals which have been filed from the adjudicatory proceedings brought about by SCN issued on 25.06.2025.
The reasoning of the Court is important because the amendment introduced an additional financial condition for exercising the right of appeal in penalty-only matters. Although amendments relating to procedure may generally apply to pending proceedings, a provision which makes the exercise of an existing substantive right more onerous cannot automatically be applied retrospectively.
The Court examined the Finance (No. 7) Act, 2025 and found that there was no indication of any legislative intention to give retrospective effect to the amended proviso. The amendment was implemented on 1 October 2025 and there was no specific provision making it applicable to those proceedings which had already been initiated before that date.
The Revenue also insisted that the petitioners first approached the authorities requesting relief from the pre-deposit, and as such, they should not be allowed to later contest the applicability of the law. However, the Court dismissed this claim and reiterated the long established doctrine that no estoppel can be applied with respect to a statute.
In other words, merely because a taxpayer initially proceeded on an incorrect understanding of the applicable legal position, such conduct cannot make a statutory provision applicable to a case to which it otherwise does not apply. An erroneous assumption by a litigant cannot give retrospective operation to a statutory amendment.[5]
Analysis and Conclusion
The ruling is important in terms of safeguarding the right to appeal for taxpayers whose cases were initiated prior to the amendment becoming effective. The court has made an important distinction between the date of passed adjudication order and an initiation date of the original case. In relation to cases initiated with a show-cause notice before October 1 2025, the right to appeal is governed by Section 107(6) valid until the date of the notice. Consequently, the subsequently introduced requirement to deposit 10% of the penalty in connection with penalty only orders cannot be established on the grounds of the fact that the ruling or appeal took place after October 1 2025[6].
The decision also reiterates a broader principle of tax jurisprudence: while the legislature is competent to prescribe conditions for exercising a statutory right of appeal, a subsequent amendment cannot ordinarily impose a more onerous condition upon a right which has already vested, unless the legislative intent to give such amendment retrospective operation is clearly evident. From a practical perspective, the judgment makes the date of issuance of the SCN particularly relevant in determining the applicable appellate regime. Taxpayers facing penalty only orders should therefore examine when the underlying proceedings were initiated before being asked to comply with the amended pre-deposit requirement.
The judgment thus provides considerable relief to taxpayers facing substantial penalty demands arising from SCNs issued before 1 October 2025. At the same time, it reinforces the settled position that the right of appeal, once vested, cannot be impaired by a subsequent amendment by imposing an additional burden unless such retrospective application is clearly contemplated by the legislature.
[1] Vineet Bhatia, GST Introduction 1–2 (n.d.)
[2] Central Goods and Services Tax Act, No. 12 of 2017, § 107(6), India Code (2017).
[3] Finance (No. 7) Act, No. 27 of 2025, § 129 (India).
[4] Gaurav Jain v. Commr., 2026 SCC OnLine Del 5519
[5] Ramaswamy Srivatsan, Delhi HC: 10% GST Penalty Appeal Pre-Deposit Cannot Apply Retrospectively, TaxGuru (Aug. 6, 2026), https://taxguru.in/goods-and-service-tax/delhi-hc-10-percent-gst-penalty-appeal-pre-deposit-cannot-apply-retrospectively.html.
[6] Agatha Shukla, Mandatory 10% Pre-Deposit For GST Penalty Appeals Inapplicable To Cases Initiated Prior To Oct 2025 Amendment: Delhi High Court, LiveLaw (Aug. 1, 2026, 5:20 PM), https://www.verdictum.in/delhi-high-court/gaurav-jain-anr-v-joint-commissioner-appeals-ii-cgst-delhi-zone-2026dhc6124-db-mandatory-10-pre-deposit-appeal-scn-stage-1618981